• Thanks for stopping by. Logging in to a registered account will remove all generic ads. Please reach out with any questions or concerns.

Trump administration 2024-2028

None of the major news outlets have picked this up, so it may in the end be nothing more than "conjecture", but boys oh boys if it's true.

Would it be Vance going behind Trump's back?
Or
Trump using Vance to purposfuuly leak the story expressly so that they could ban Politico?

 
None of the major news outlets have picked this up, so it may in the end be nothing more than "conjecture", but boys oh boys if it's true.

Would it be Vance going behind Trump's back?
Or
Trump using Vance to purposfuuly leak the story expressly so that they could ban Politico?

Status News is generally regarded as a factual left-center outlet that hasn’t failed any fact-checks. It also has covered negative aspects of politicians in the left as well, so there may be some fire here. I guess we’ll know more if it unfolds or disappears

 
None of the major news outlets have picked this up, so it may in the end be nothing more than "conjecture", but boys oh boys if it's true.

Would it be Vance going behind Trump's back?
Or
Trump using Vance to purposfuuly leak the story expressly so that they could ban Politico?

1790281764018.png
 
I'm confused. If by "leaker" you mean the 'unnamed senior official" that "leaked" information about an impending Iran deal, it has been established that the unnamed official was Vance, and all reporters in the room were told to refer to him as an unnamed senior administration official. Trump used that instance in the legal submissions as proof that the outlet in question was a national security risk.

What am I missing?
 
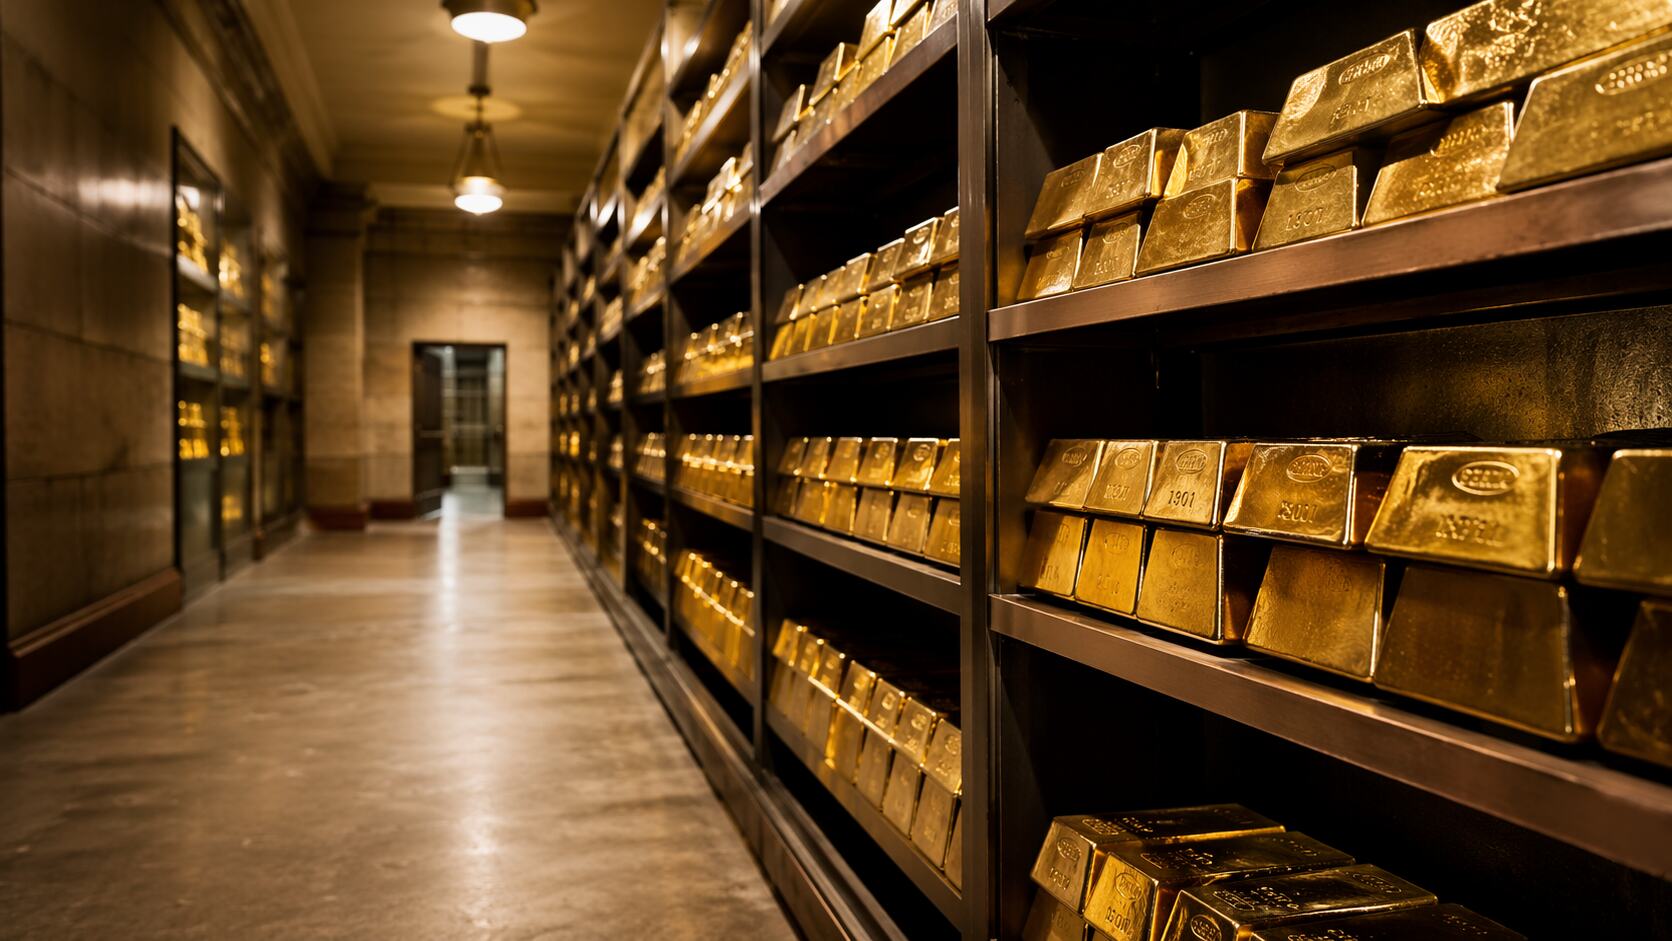
Didn't The Netherlands just repatriate a horde from Canada back to the Old Country?

From earlier this month

The Dutch central bank announced Wednesday (Sep 2) that it has moved billions of dollars worth of its gold reserves out of North America in a move it described as “crisis preparedness” in a time of global political unrest.

It said that between March and August, some 86 metric tons of gold were transferred to London from the combined total of around 313 metric tons held in New York and Ottawa. Before the move, New York housed 31.3 per cent of the Dutch gold and Ottawa held 19.7 per cent. After the move, both cities now hold 18.5 per cent, the bank said.

The bank owns 612.4 metric tons of gold that was worth €72.2-billion (about US$83.6-billion) at the end of 2025.
 
From earlier this month


A bit of a stereotype, IMHO ;)

Austin Powers Love GIF
 
AI’s take on this week’s Treasury auction of 2, 5 and 7-year treasury notes. Vegas bookies are betting it’s going to get worse…5-year notes are the ‘belly’ of the Treasury’s offerings to help service the federal debt.

📌 2-Year Note: The "Policy Path" Safe Haven
The short-term $69 billion auction cleared cleanly. The bid-to-cover ratio of 2.63x edged out its previous historical baseline, and the 0.2 basis point tail was practically negligible ("on the screws"). Front-end investors were comfortable locking in yields near 4.79% because the front-end remains heavily anchored by the immediate Federal Reserve terminal rate trajectory. [1, 2, 3]

⚠️ 5-Year Note: The Epicentre of the Sell-off
The $70 billion 5-year auction was a statistical disaster, labeled one of the weakest sales since 2018. Investors flat-out rejected pre-auction trading levels, forcing a gargantuan 3.1 basis point tail over the 5.002% when-issued yield. The bid-to-cover collapsed to 2.21x, requiring Primary Dealers to heavily absorb the unsold supply. [1, 2, 3]

📉 7-Year Note: The Expected Spillover
Suffering from the negative momentum of the 5-year sale, the 7-year note cleared at 5.085%, marking a 33-year high dating back to April 1993. Demand indicators lagged across the board with a weak 2.42x bid-to-cover and a telling 0.7 bps tail, confirming that international buyers (indirect bidders) pulled back their participation. [1, 2, 3]


📈 How This Affected Current Bond Market Assessments

These successive failures outside the immediate short-term space have profoundly shifted consensus trading narratives in a few distinct ways:
  • Re-pricing the Supply "Term Premium": The primary driver of this week's breakdown isn't just the Fed—it's pure fiscal physics. Markets are waking up to the reality that the massive deluge of intermediate coupon supply ($183 billion auctioned in three days) is overwhelming organic market demand. Investors are aggressively demanding a steeper "term premium" (extra yield concession) to step in and absorb federal deficits. [1, 2, 3, 4]
  • Severe Curve Steepening & The 5% Threshold: Following the 5-year failure, intermediate yields violently broke out. For the first time in years, a massive portion of the intermediate belly of the curve shifted above 5.00%. The broader 10-year Treasury has also climbed over 5.14% as global sell-offs feed into domestic debt. [1, 2, 3, 4, 5, 6]
  • "Higher-for-Longer" Cemented by Inflation Fears: The fact that the intermediate belly bore the brunt of the damage reflects escalating, energy-sensitive long-term inflation expectations. Bond desks are positioning for a stickier economic reality where yields must stay structurally high, reducing the expected tally of future Fed rate cuts. [1, 2, 3]
 
Back
Top